
Analysis: Trump Accounts
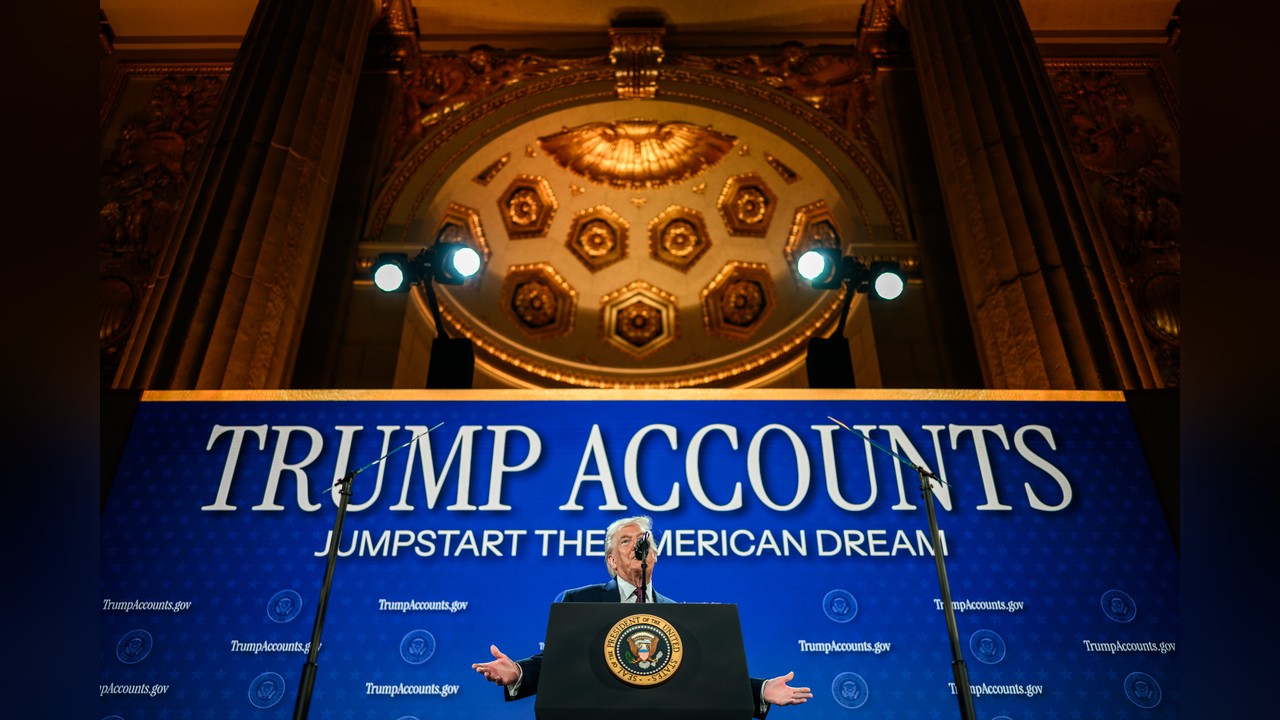
The Default Wealth Engine: Analyzing the Rollout of Trump Accounts for U.S. Minors
The U.S. government is initiating a massive financial pivot by introducing “Trump Accounts,” a specialized IRA vehicle designed for children. The program aims to automate wealth building for an estimated 73 million children, utilizing a default investment fund structure to ensure immediate market entry. While marketed as a tool for early-life wealth accumulation, the initiative has sparked a regulatory and political debate over fund selection, investment restrictions, and the efficacy of government-managed savings versus direct tax relief.
Market and Systemic Impact
The scale of the Trump Account rollout represents a significant shift in retail capital flow. By funneling 73 million accounts into a single default investment fund, Washington is creating a concentrated pool of capital that could exert substantial influence on the assets within that fund. The systemic risk lies in the “default” nature of the accounts; the compounding difference between the default fund’s performance and optimized alternative selections will materialize over an 18-year horizon, potentially creating a wide wealth gap based solely on parental intervention.
The program competes directly with existing savings vehicles, including 529 plans, custodial Roth IRAs, and Uniform Gifts to Minors Act (UGMA) accounts. Unlike these voluntary instruments, the Trump Account is being positioned as a government-driven mechanism, with some state leaders, such as California Governor Gavin Newsom, promoting it alongside state-specific programs like CalKIDS as “free money” for families.
Comparative Data Analysis
The following table delineates the current regulatory framework and the competitive landscape of the Trump Account relative to traditional youth savings vehicles.
| Feature | Trump Account | 529 Plan | Custodial Roth IRA | UGMA Account |
|---|---|---|---|---|
| Primary Purpose | General Wealth Building | Education Savings | Retirement/Long-term | General Asset Transfer |
| Default Mechanism | Auto-open/Single Default Fund | User-selected | User-selected | User-selected |
| Investment Control | IRS-proposed “Eligible” list | State-managed options | Broad Market | Broad Market |
| Restriction Period | Until age 17 | Education-linked | Retirement-linked | Age of Majority |
| Funding Source | Govt/Parental | Parental/Third Party | Earned Income | Parental/Third Party |
Investment Constraints and Regulatory Oversight The IRS has proposed strict regulations regarding the composition of these accounts. Under the proposed rules, funds are restricted to “eligible investments” from the date of account establishment until the beneficiary reaches the age of 17. This restriction limits the agility of the portfolio during the most critical compounding years of the account’s lifecycle.
Political and Public Friction
The rollout has encountered significant ideological resistance, particularly at the state level. In California, the promotion of Trump Accounts by the executive branch has been met with public skepticism. Voter sentiment indicates a preference for direct tax reductions over government-managed investment accounts, framing the “free money” narrative as a secondary priority to immediate disposable income.
This friction highlights a broader tension: the government’s desire to institutionalize long-term savings versus the public’s demand for immediate fiscal relief. The “fool’s gold” critique suggests that the perceived benefit of the account may be offset by the lack of autonomy in investment selection and the potential for underperformance of the default fund.
Forward Outlook
The trajectory of Trump Accounts depends on two primary variables: the finalization of IRS “eligible investment” lists and the rate of parental opt-outs from the default fund.
If the default fund underperforms the broader market, the 18-year compounding effect will result in a systemic loss of potential wealth for millions of minors. Conversely, if the IRS allows for a diversified and aggressive eligible investment list, the program could successfully bridge the wealth gap for lower-income demographics who lack access to traditional financial planning.
Immediate attention will be focused on the transition period as beneficiaries approach age 17, the point at which investment restrictions lift. This window will likely see a massive migration of capital from “eligible” government-approved assets into broader market instruments, creating a predictable cycle of volatility within the specific assets currently favored by the IRS.